Home Sellers
How do I price my Cape Coral home when I see so many price cuts?
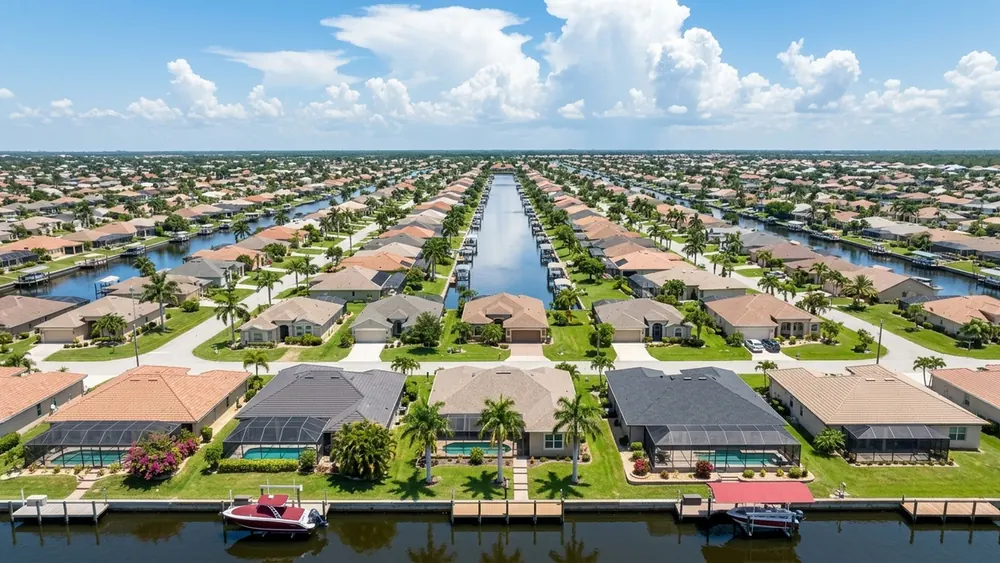
Price from recent comparable sales first, and read price cuts as lessons about other listings, not verdicts on yours. Then weigh dated inventory, days on market, condition, and any water access before you settle on a number you can stand behind.
On this page
Start with comparable sales, not price cuts
Price your Cape Coral home from recent comparable sales first, then use price cuts as context rather than a target. A price cut tells you that a particular seller started at a number buyers did not accept. It does not tell you what your home is worth, and it does not mean you should start low to stay ahead of the market. The order matters: what similar homes actually sold for, then what is competing with you today, then what your house brings to the table.
Here is why that order matters. When you scroll listings and see reduction after reduction, it is easy to feel pushed in one of two directions. Some sellers panic and price well under what the evidence supports. Others decide the cuts happened to other people and list high anyway. Both reactions skip the homework. A price built from dated sales and an honest look at your house gives you a number you can explain to a buyer, and to yourself, when the first offers come in.
Price cuts are still useful information. They show you where other sellers misjudged what buyers would pay, and they can point to features or condition issues buyers are pushing back on. The trick is reading them in context, alongside the other measures in a market snapshot, instead of treating each one as a headline about your own home. Read that way, a page full of reductions becomes a lesson rather than a source of worry.
What a price cut can and cannot tell you
A single price cut is a story about one listing. The seller may have started high, the home may have needed work, the photos may have missed the point, or insurance questions may have slowed buyers down. Before you read anything into a reduction, ask what else was going on with that property and how it compares with yours. Here is what a cut on a nearby listing can and cannot tell you when you are setting your own price.
- It can show that the original asking price was above what buyers would pay
- It can hint at features or condition issues buyers weighed against that home
- It cannot tell you the final sale price until the sale actually closes
- It cannot tell you what your own home, with its own condition, is worth
The market measures worth reading together
Julie shares Cape Coral market snapshots that break the market into a handful of measures, and the habit is worth borrowing: look at them together and compare each one over time, with dates and a named source attached. No single figure prices a home. Taken together, they show how much choice buyers have and how they are behaving right now. When you sit down with the numbers, ask about each of these.
- Recent comparable sales, closed rather than listed, for homes like yours nearby
- Current inventory, meaning how many similar homes a buyer can choose from today
- Days on market, and how that measure has moved across recent months
- How often similar listings have reduced, and at what point in the listing the cut came
- Median list price, read as a trend over time rather than a single snapshot
Why your house is not the average
Market measures describe the middle of the market. Your home is one specific house, with its own roof, systems, layout, and lot. Two homes that look alike on a listing sheet can sell very differently once a buyer walks through, and once a buyer’s insurance agent and inspector weigh in. That is why the comparable sales you use should be close in features as well as location, and why condition belongs in the pricing conversation from the start.
Condition is where a lot of price cuts begin. A buyer who sees an older roof, an aging pool enclosure, or tired equipment often prices those items in, and sometimes prices in more than the repair would cost. Having built and remodeled homes, Julie looks at a house as a physical thing: what works, what is near the end of its life, and what a buyer is likely to ask about. Knowing that before you set a price means fewer surprises after.
Water access changes the picture too. A home on the water should be compared with homes that have similar access, and the route to open water, the dock, and the seawall all deserve confirmation from the City of Cape Coral or a marine professional before you lean on them in a price. An inland home is compared on its own features. Mixing the two in one set of comparables is one of the quickest ways to land on a misleading number.
Insurance questions shape what buyers will pay
In Cape Coral, buyers often talk to a licensed insurance agent before they make an offer, and what they learn can change how much they are willing to pay. Coverage depends on things like the age and condition of the roof, the systems, and the property’s details, and it changes over time. As a seller, you cannot answer those questions for a buyer, but you can make the information easy to find so the insurance step does not stall a sale.
Gather what you have on the roof, the electrical, plumbing, and air conditioning systems, any storm protection, and any permitted work. Records do not set a price, but they help a buyer and their insurance agent get clear answers sooner. That keeps the conversation about your house moving instead of turning into a list of unknowns. If you are unsure which details tend to matter most, ask a licensed insurance agent rather than guessing.
Read a price cut as a lesson about someone else’s listing, not a verdict on your home. I’d rather we price from real sales and an honest look at the house.
Habits that lead sellers to chase the market
Chasing the market down usually starts with an asking price that ignores the evidence. The home sits, buyers notice, and each reduction feels like a reaction rather than a plan. The opposite mistake happens too: a seller sees cuts everywhere and lists well below what recent sales support, leaving room on the table before a single buyer has seen the house. In both cases, the price came from a feeling about the market instead of a careful read of it.
A few other habits cause trouble. Using list prices instead of closed sales as comparables. Relying on figures with no date attached. Comparing a waterfront home with inland ones, or a home that needs work with one that has been updated. And deciding on a reduction schedule before the listing has had a chance to gather feedback. Each of these is fixable with a calm look at dated, sourced information and a clear plan for what you will do if early showings are slow.
Gather this before your pricing conversation
Before you talk about price, write down what you know about your house: the age of the roof and major systems, any updates and roughly when you made them, the condition of the pool and enclosure, and, if you are on the water, what you know about the dock and seawall. Rough notes are fine. The point is to bring the house’s real story into the room so comparable sales can be matched to it fairly.
Then pull together what supports those notes: permits, receipts, warranties, inspection reports, and insurance documents. If you are unsure about anything, such as permit history, the City of Cape Coral holds those records, and a licensed home inspector can tell you how the house reads today. Questions about disclosure belong with official Florida sources or a real estate attorney. Having this ready keeps the pricing talk focused on evidence instead of guesswork.
If you are thinking about selling a home in Cape Coral and the price cuts have you second-guessing, bring the question to Julie, a Florida real estate agent with Starlink Realty, Inc. The conversation starts with recent sales and the house itself, and nothing about price or timing is promised. You can walk away with a clearer picture and no obligation. Which part of your home do you think a buyer will ask about first?
This article is general information about buying and selling property in Cape Coral and Lee County, Florida. It is not legal, tax, insurance, lending, valuation or inspection advice and does not predict prices or promise results. Confirm insurance with a licensed insurance agent, water routes, docks, seawalls and permits with the City of Cape Coral and a marine professional, condition with a licensed inspector, homestead and taxes with the Lee County Property Appraiser and Tax Collector, and financing with a lender. Julie Kubic, Starlink Realty, Inc.
Written by